


Gold kicks off the Tuesday session on the back of a strong session on Monday, but without straightforward assistance from falling real yields. The COMEX December 2026 gold futures settlement price was $3,969.60 per troy ounce, a gain of $70.70. This is interesting because it establishes the move, but does not establish the cause.
The distinction becomes important when comparing gold with the Treasury market. The official 5-year real par yield rose to 2.31% yesterday from 2.25% on Friday, while the 10-year measure increased to 2.62% from 2.60%. The chart just below includes every business-day observation from October 26 through yesterday.
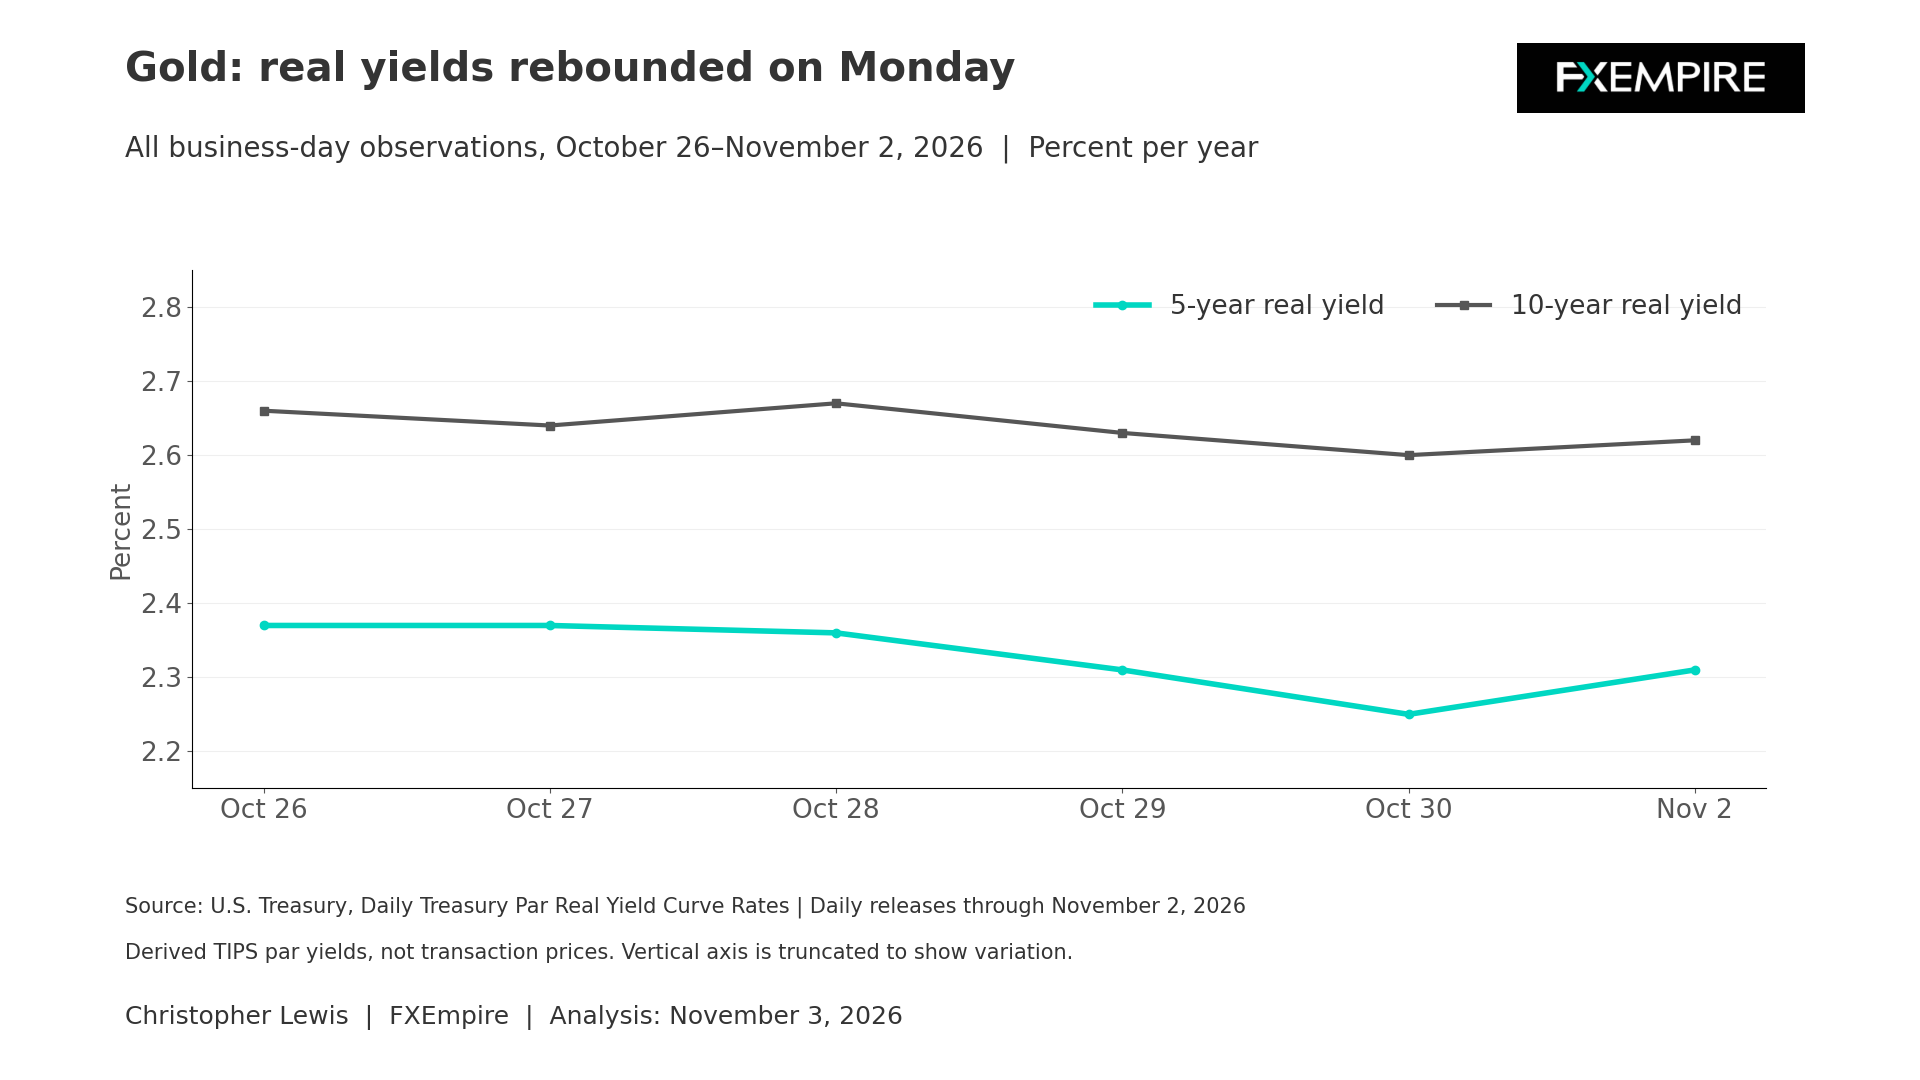
Push and Pull of Gold Markets
Other influences can dominate a session. My interpretation is that Monday’s combination argues against explaining every gold rise through lower real borrowing costs. Higher real yields can also increase the opportunity cost of holding a metal that pays no interest, but that relationship is not necessarily mechanical as far as pricing is concerned.
For example, yesterday we received word that the Iranians were looking to talk to the Americans again, so maybe a little bit of short covering entered the fray. The fact that this was part of the session also limits what can be concluded about the durability of the rise in price.
A price advance alongside rising yields demonstrates resilience for the session, but it does not establish that financing conditions have stopped mattering. A stronger fundamental foundation would involve evidence that gold can retain its demand across different interest-rate outcomes, rather than making one day the complete argument.
Fed Looking to Hike in December?
The policy backdrop remains restrictive enough to deserve some attention. On October 28, the Federal Reserve held its target rate range at 3.75% to 4.00%. Two dissenters preferred a quarter-point increase. That was a completed policy decision, but when you look at the Federal Reserve outlook, most traders believe it will hike 25 basis points in December.
Gold Price Forecast
Every new Gold analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Gold forecastsInflation provides part of the reason to keep the Fed in mind. The BEA’s October 29 release showed September PCE inflation and core inflation of 3.6% year-over-year and 3.1%, respectively. The monthly increases were 0.5% and 0.3%, respectively.
For gold, persistent inflation can cause some chaos. It can strengthen interest in preserving purchasing power, but at the same time encourage tighter monetary policy and higher real returns elsewhere, specifically in the bond market. Which asset dominates depends on how investors assess the policy response and the credibility of inflation control.
JOLTS Coming Today
Today, we get the September JOLTS number in the United States at 10:00 a.m. EST. This could provide another piece to the puzzle. On Thursday, we get preliminary third-quarter productivity and costs, and on Friday, we get the nonfarm payrolls announcement at 8:30 a.m. EST.
These all can have an influence on the gold market, with special attention paid to the Friday announcement. The useful questions at this point will be whether labor demand appears to be cooling and whether incoming evidence changes the balance between inflation pressure and growth resilience. Softer labor demand could weaken the argument for additional restraint, although the effect on gold would probably still depend on the response of yields and currencies.
For Tuesday, the market finds itself verifying a stronger prior settlement and a modest rebound in real yields, with meaningful labor data ahead this week. No fresh central-bank purchase investment-flow surge or official news was seen overnight directly related to the market.
Technical Analysis
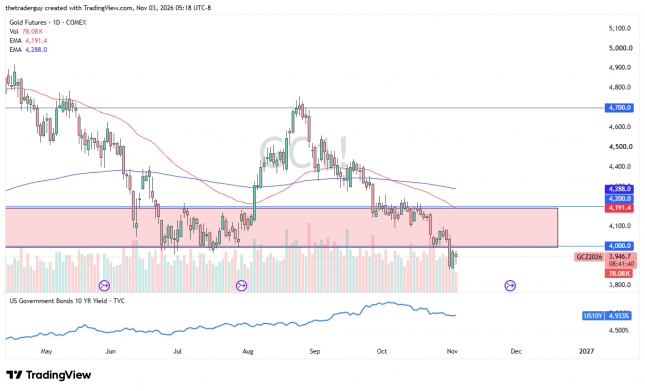
From a technical-analysis standpoint, it looks like the $4,000 level could be tested for resistance. Quite frankly, if the market were to rise above that level, I would not trust that rally until we get through the employment figures on Friday. It is very possible this could be simple short covering. I still prefer to fade rallies as long as real yields remain so strong.