


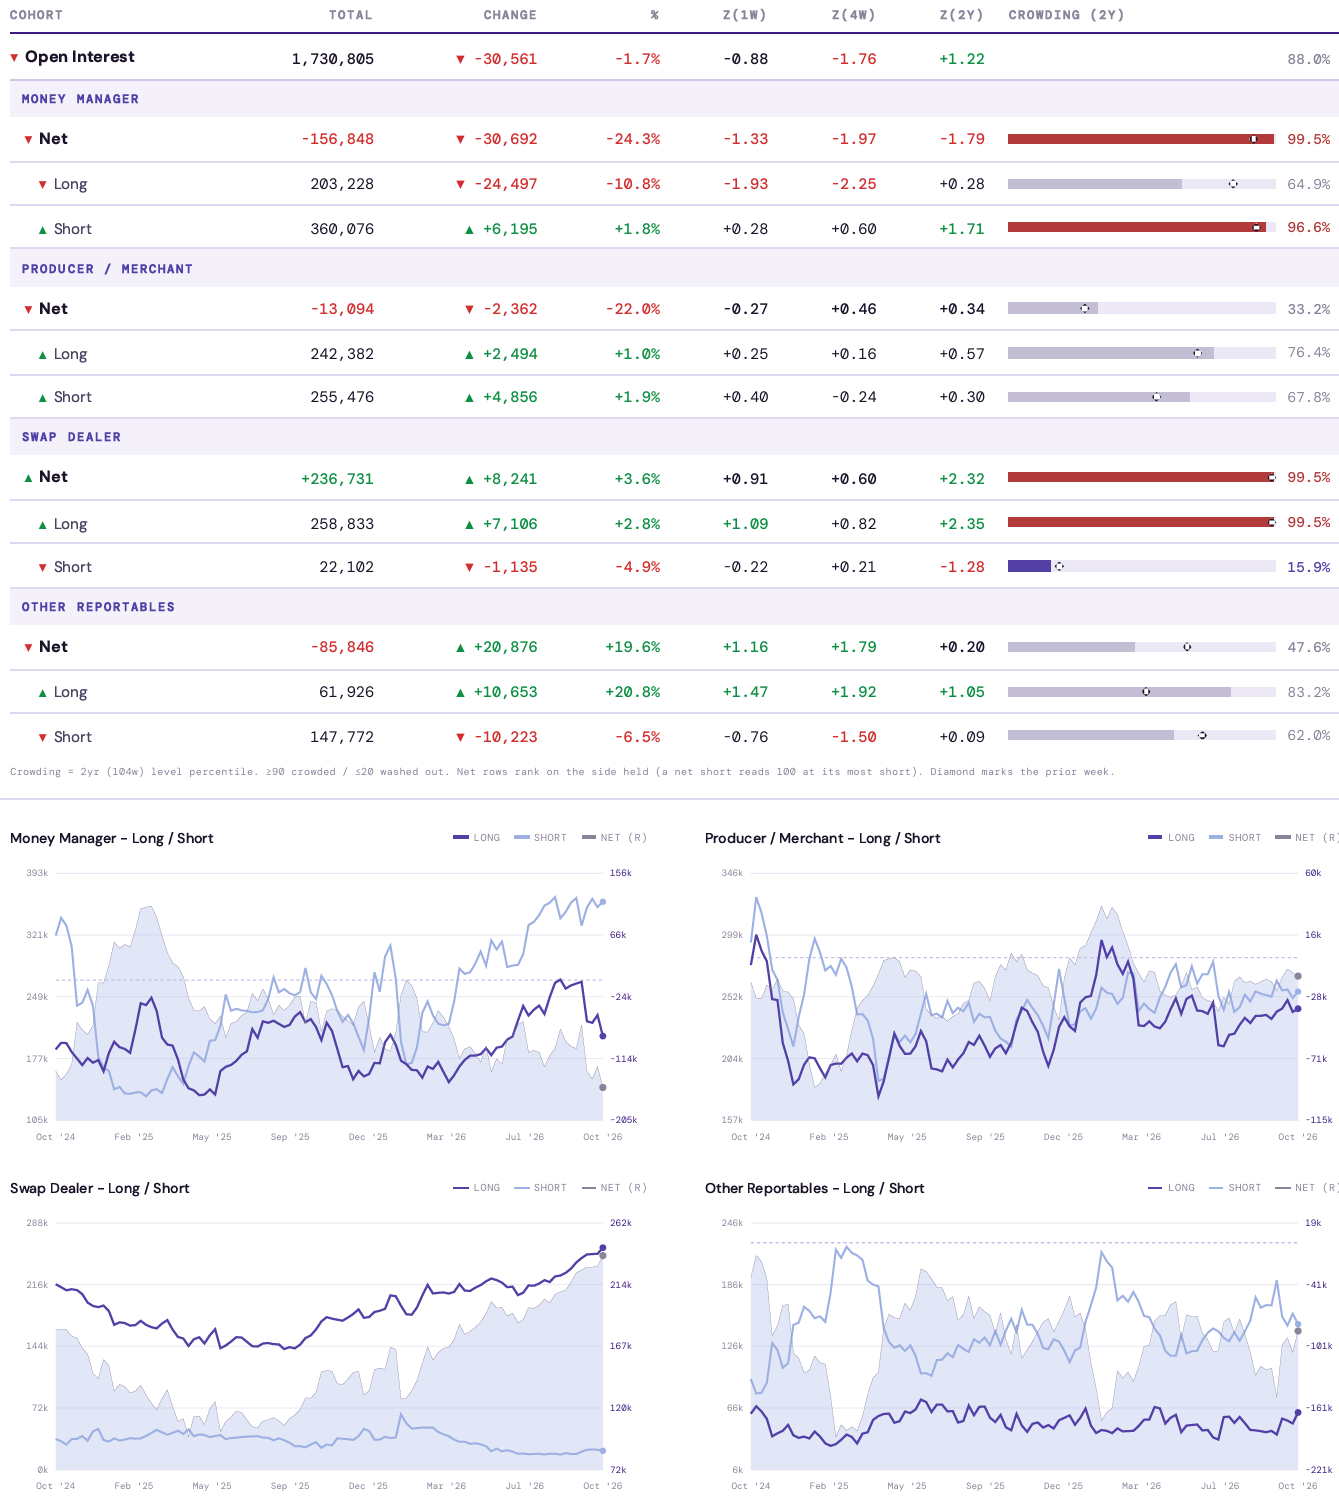
Henry Hub Natural Gas dropped about 15% this past week. The standard easy answer most reports are giving is “a warmer winter outlook”. This isn’t the first time we have heard that this winter, this has been the story each week, but each other week didn’t drop 15%, so what changed? Until now, we’ve been slowly pricing the warmer winter, but we have been cautious of a cold snap. Considering how crowded short the natural gas market has been these past few weeks, any sign of a cold snap would have created a considerable short squeeze. Last week, speculators have given up waiting on a short squeeze. Managed money cut their long positions by over 10% as of the 20th of October, one of the largest cuts to long positions in the last 2 years (see more in COT section).
Henry Hub: A Classic Tale of Supply and Demand
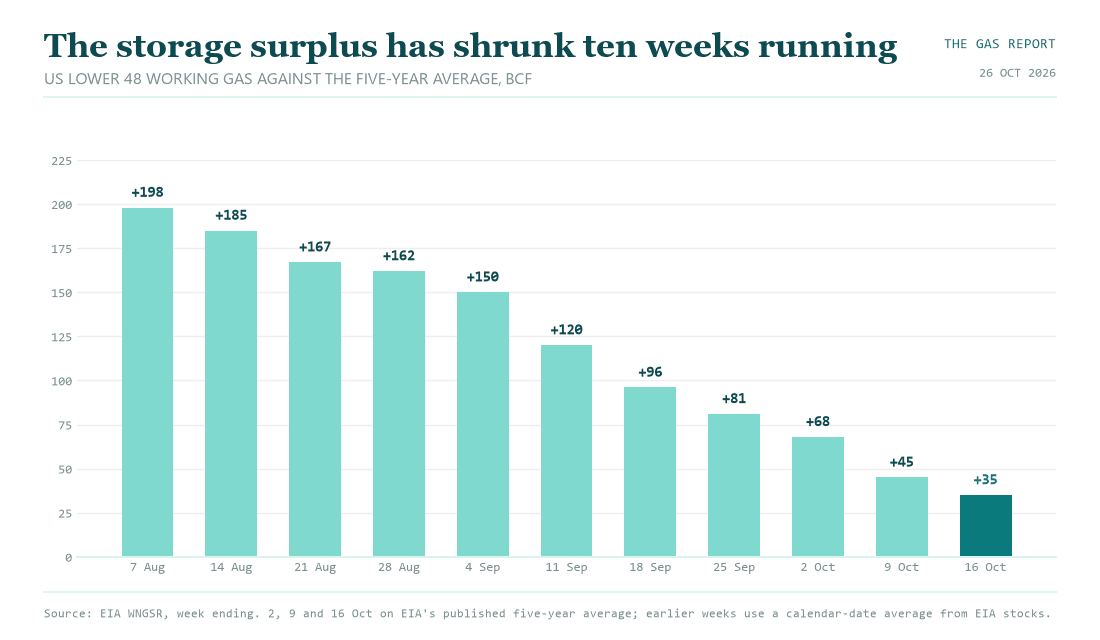
Nothing in the physical market explains it. The storm shut in about 1.26 Bcf/d at its peak, roughly 1% of US output, and the gas is back: production was 113.8 Bcf/d on Thursday, 4% above its low during the storm (BNEF). LNG feed gas ran at 20.6 to 20.9 Bcf/d, at or near records. Thursday’s storage build, +77 Bcf, came in below the five-year average, and the surplus has shrunk ten weeks running, to +35 Bcf. What changed was the tape. Once $3 gave way on Tuesday, technical selling accelerated on Wednesday, and funds waiting for the cold, stopped waiting. The balance didn’t turn bearish. The positioning did.
Fear and Fact
TTF finished the week at a multi-year high of €93.85/MWh, up 7.2% on the week. We were actually down about 2.8% on the week after Tuesday’s close. Price jumped for the rest of the week on strike-plan headlines. That is even greater risk being priced in. However, I reiterate not for the first time, that below this fear premium, is genuine structural supply and storage issues. No doubt the risk premium is growing and accounts for a lot of the price action we have seen, but the underlying price excluding risk premium is also rising. This means if we had a deal come into play today and everything was sunshine and rainbows, while of course price would drop heavily, we would not return to normal.
The Clock Is the Midterms
The strait has a date on it now. The NYT and ABC both reported that the US and Israel have drawn up plans for renewed strikes on Iran, and the NYT says they would come after the 3 Nov midterms. No named official has confirmed it. On Friday Trump said, “we could end the Iran war very quickly.” Iran’s own offer is still on the table: the US lifts its blockade and oil sanctions, a ceasefire on all fronts follows, and the strait reopens on day six. Washington has not said yes. The issue is order, not content. Iran wants the blockade and sanctions removed first before discussing nuclear, the US wants the nuclear issue dealt with. Looks to me like the problem is Iran don’t want to give up leverage, and Washington wants out without looking like they lost. For now, TTF is pricing the risk, after the midterms we will price the decision.
Natural Gas Price Forecast
Every new Natural Gas analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Natural Gas forecasts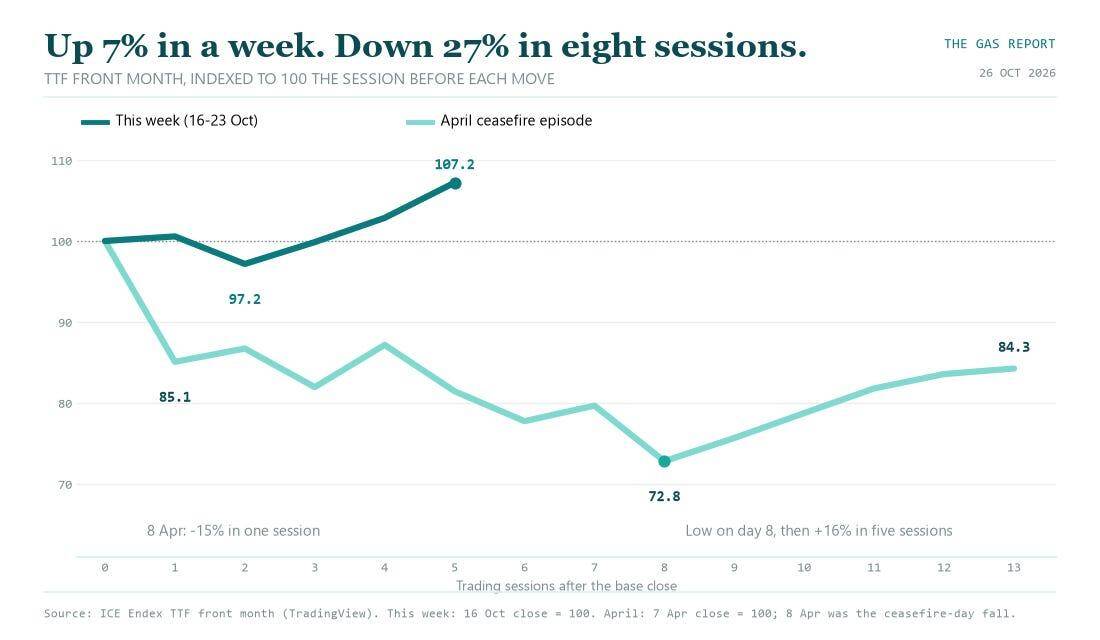
EIA Report
The 77 Bcf build for the week ending 16 October was a hair below the 78 Bcf analysts expected. A year ago the build was 86 Bcf and the five-year average for the week is 87 Bcf, according to EIA. Stocks reached 3,644 Bcf, 35 Bcf (1.0%) above the five-year average and 152 Bcf below a year ago. In line with the forecast but small against the seasonal norm, so the surplus shrank for a tenth straight week, from +198 Bcf on 7 August and they continue to sell. The leak over the last three weeks: -11, -23, -10. Smaller than normal again: the surplus is still bleeding, and the price is selling it. More in the EIA Gas Inventory.
The Net Net
TTF. Last week I leaned slow up, fast down, and after this run I’d lean harder that way. A 10% move since Tuesday’s close has priced in a lot of fear, and it’s clear the way the market thinks the cards will fall: it’s paying for strikes after the midterms, so from the third of November, it bleeds a little more each day they don’t arrive. There is of course still an upside case. If the military strikes do come soon after the third, we will continue steadily up, but don’t expect a big jump as the market anticipates these attacks already. A jump up would require a genuine surprise such as strikes landing early, before the midterms end. Everyone is speculating whether we will or won’t get strikes after the midterm, strikes occurring now would legitimately catch the market off guard.
If we do get a deal, we gap down hard as the risk premium goes, but I’d expect the market to overshoot and claw part of it back. A deal doesn’t put gas in storage. Europe is still 15 points short with the injection season nearly over, so the shortage under the fear is still present once the fear has gone. I’d sell the headline, then watch it recover.
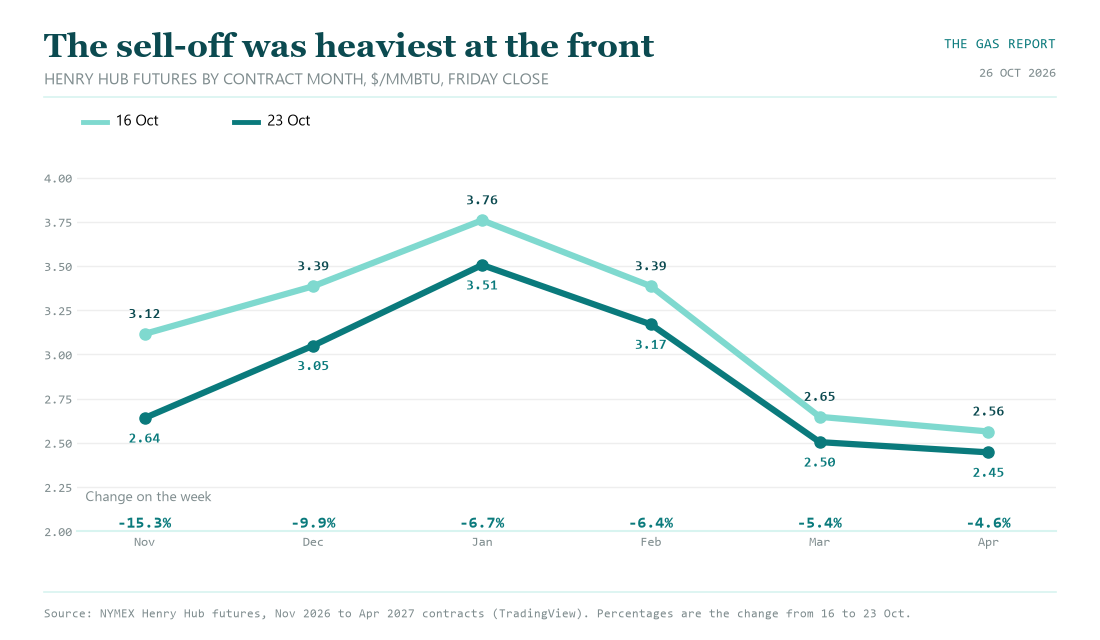
Henry Hub: The market sold the start of winter, not the heart of it: November and December fell 14% to 15% while January and February only fell about 6%. Managed money is the most net short in two years, so any real move higher forces covering. The storage surplus has also shrunk ten weeks running, to +35 Bcf. The risk is to the upside, but it needs a catalyst: a colder 8 to 14 day map, or a storage build below the five-year average. Continued warmer weather reports would keep the downside risk real, but mainly on the December and January contracts which, both sitting above $3, have further to fall.
Commitment Of Traders Report
$NG: Funds are the most net short they’ve been in two years: 157k, up 24% on the week, past the previous extreme of 146k in November 2024. Four fifths of that move was longs leaving (-24.5k, -10.8%), not new shorts, which rose only 1.8%. The banks ie. Swaps, hold the other side, net long 237k, and both cohorts read 99.5 on the two-year crowding scale. There’s no doubt, we are overcrowded short, but that doesn’t mean we can’t get even more short before we get a squeeze. As already stated, we need an upside driver.
What’s the Next Move?
I was bang wrong in the long call in the last report. I am not chasing the shorts down here. I am very much looking for that long catalyst and identifying good areas in which to do so.
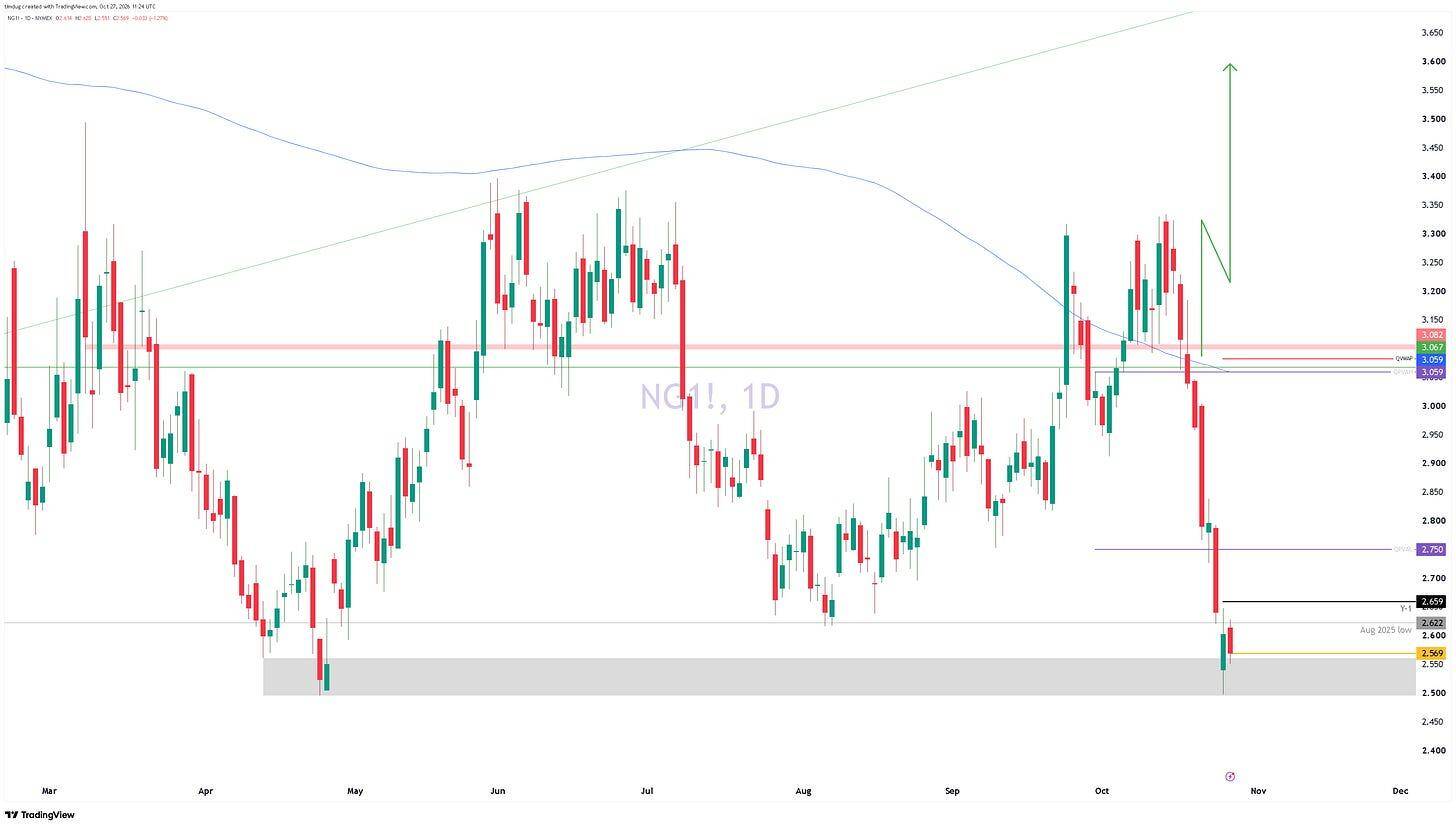
So here we are on the April 2026 lows. With MM slowly coming to the ‘out of bullets’ levels, we must remain vigilant to the upside. Don’t forget though, this is widow maker city. From order flow trading to seasonal trades, this market, as slow as it can be, will rip your face off.
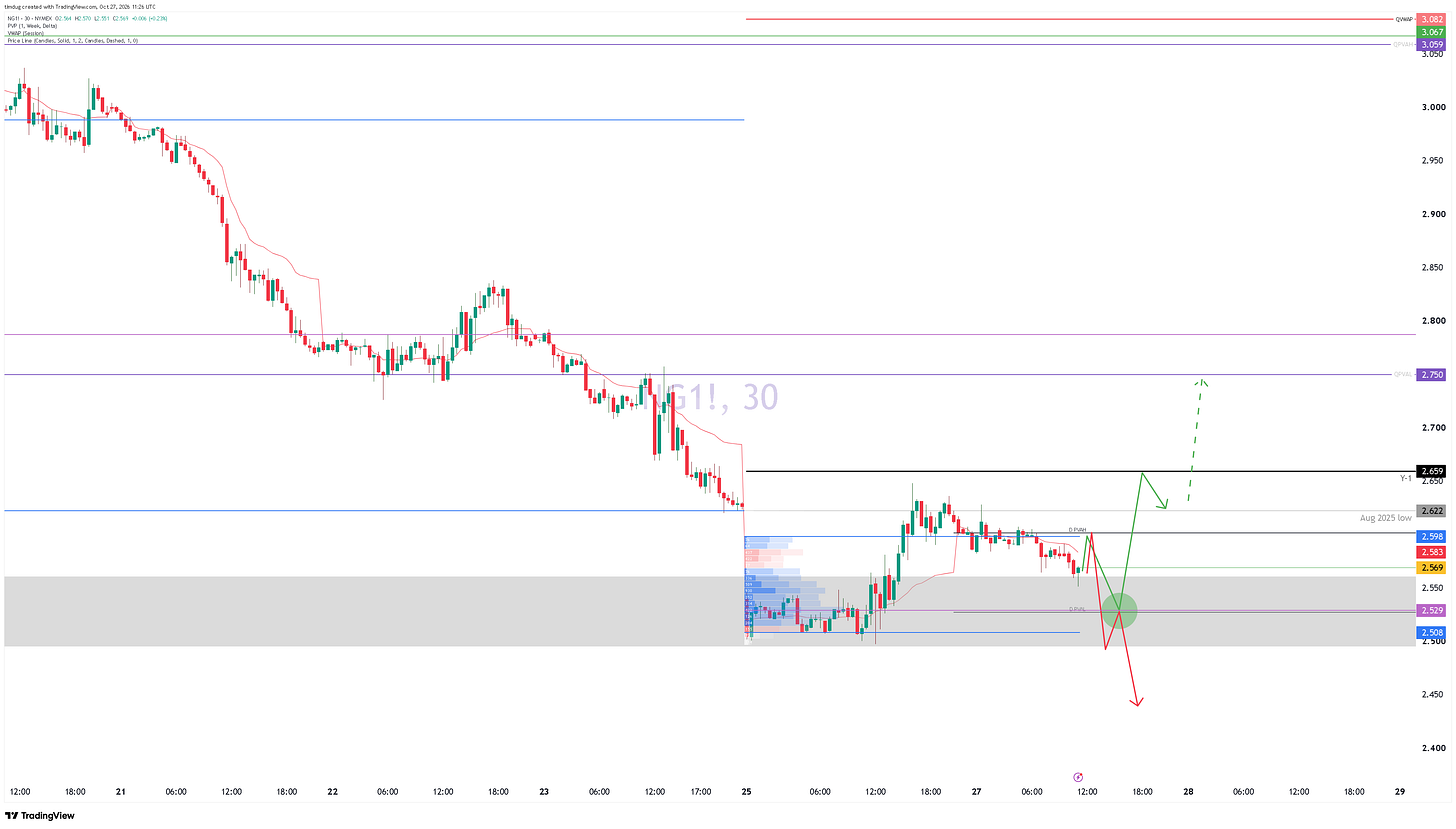
That said, I’m interested to watch order flow in this area as below.
That’s the report!