


Natural gas has entered the week with inventories above the seasonal norm, and Tuesday has seen a bit of a push to the upside. The Henry Hub outlook is somewhat balanced between adequate aggregate supply and the possibility of tighter regional conditions as winter approaches.
U.S. Storage
The EIA Weekly Natural Gas Storage Report, released on November 5 for the week ending October 30, estimated total working gas at 3,801 billion cubic feet. Stocks rose by 77 billion cubic feet during the week. They were 109 billion cubic feet, or 2.8%, below the year-earlier level of 3,910 billion cubic feet, yet 54 billion cubic feet, or 1.4%, above the five-year average of 3,747 billion cubic feet.
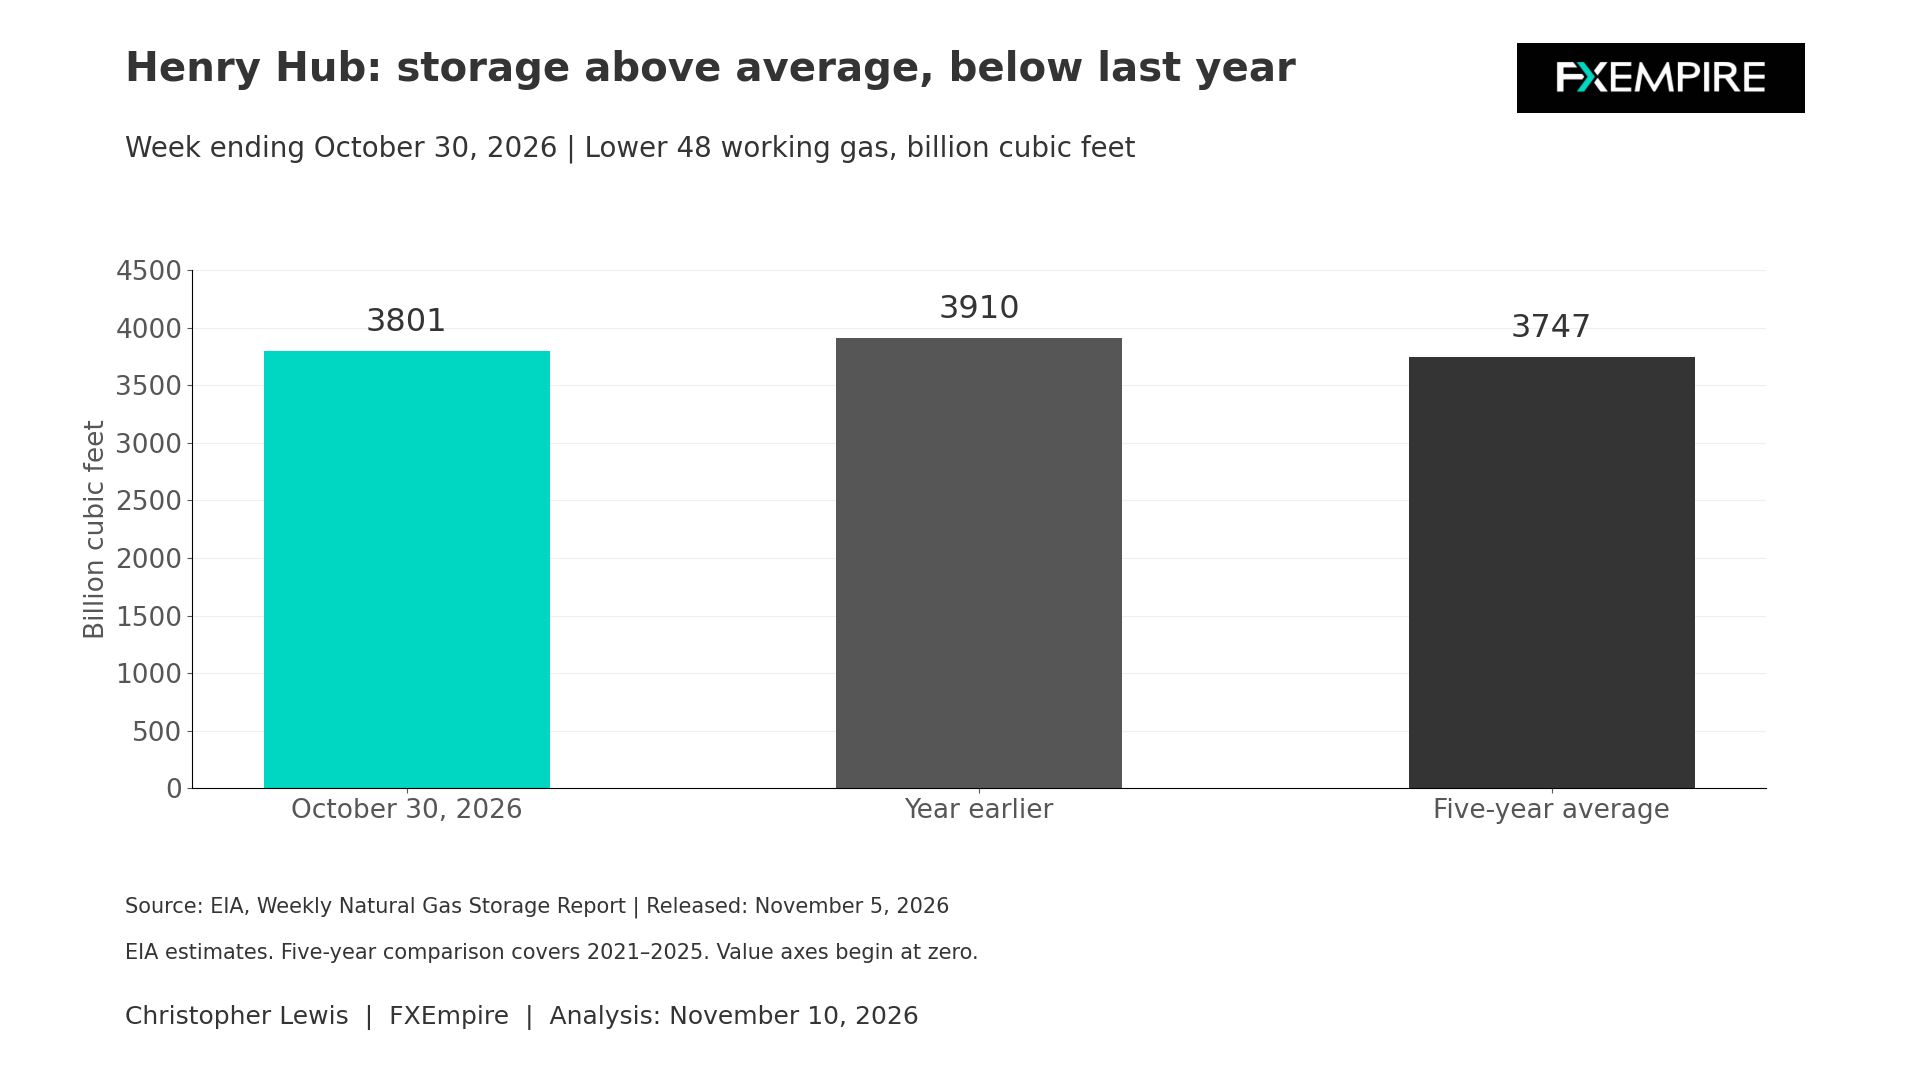
The regional breakdown of storage shows why the national total needs to be observed a little closer. The East added 13 billion cubic feet to reach 926 billion cubic feet, and the Midwest added 32 billion cubic feet to reach 1,111 billion cubic feet. The Mountain region increased by 2 billion cubic feet to 260 billion cubic feet. Pacific stocks slipped by 1 billion cubic feet to 296 billion cubic feet.
The South Central region accounted for 40 billion cubic feet of the entire injection, bringing working gas there to 1,208 billion cubic feet. Within South Central, salt facilities added 22 billion cubic feet, and non-salt facilities added 18 billion cubic feet. Despite the fairly large-sized build this past week, South Central stocks remain below both their year-earlier level and their five-year average. This could become an issue if LNG demand or early heating requirements intensify near the Gulf Coast supply and pipeline corridors.
The Key Question Will Be How Quickly Injections Give Way to Withdrawals
The 77 billion cubic feet injection is an estimate for the storage week, not necessarily a forecast. It shows the system continued building inventories at the end of October, but it does not reveal production, LNG feed gas, or power-sector demand today.
Natural Gas Price Forecast
Every new Natural Gas analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Natural Gas forecastsThe late transition would leave storage comfortable relative to normal. A sharp early cold spell could erode the 54 billion cubic feet surplus to the five-year average, especially because stocks already trailed last year.
Official weather reports point to divided risk across the country. NOAA’s Climate Prediction Center discussion yesterday assigned elevated probabilities of above-normal temperatures across most of the country, from the Pacific region through the lower Mississippi Valley and western Great Lakes, for November 14-18, with the strongest probabilities in the Northern Plains. It indicated near- to below-normal temperatures across parts of the eastern United States.
For November 16-22, the CPC favored above-normal temperatures east of the Rockies, particularly in the north-central states, while the West leaned near to normal or just below it. These are probabilistic outlooks, not measured temperatures, and, of course, weather forecasts can and will change from time to time.
Warmth Could Cause Issues
Broad warmth would normally restrain heating demand and slow the move into withdrawals, but eastern cold can matter disproportionately because of the population centers of New York, Boston, Pittsburgh, etc.
The next storage report is scheduled for Friday, and it will show conditions for the week ending November 6 and provide the first official test of whether the late-season injection pace has persisted. Traders should also watch regional weather revisions, LNG terminal operations, and pipeline notices from official operators.
The near-term narrative in the natural gas market is somewhat conditional. Storage above the five-year average and broad forecast warmth weaken the scarcity case. Stocks below last year, a South Central deficit to normal, and any colder shift in the East, which we are already starting to see, could reinforce the market.
Technical Setup on Charts
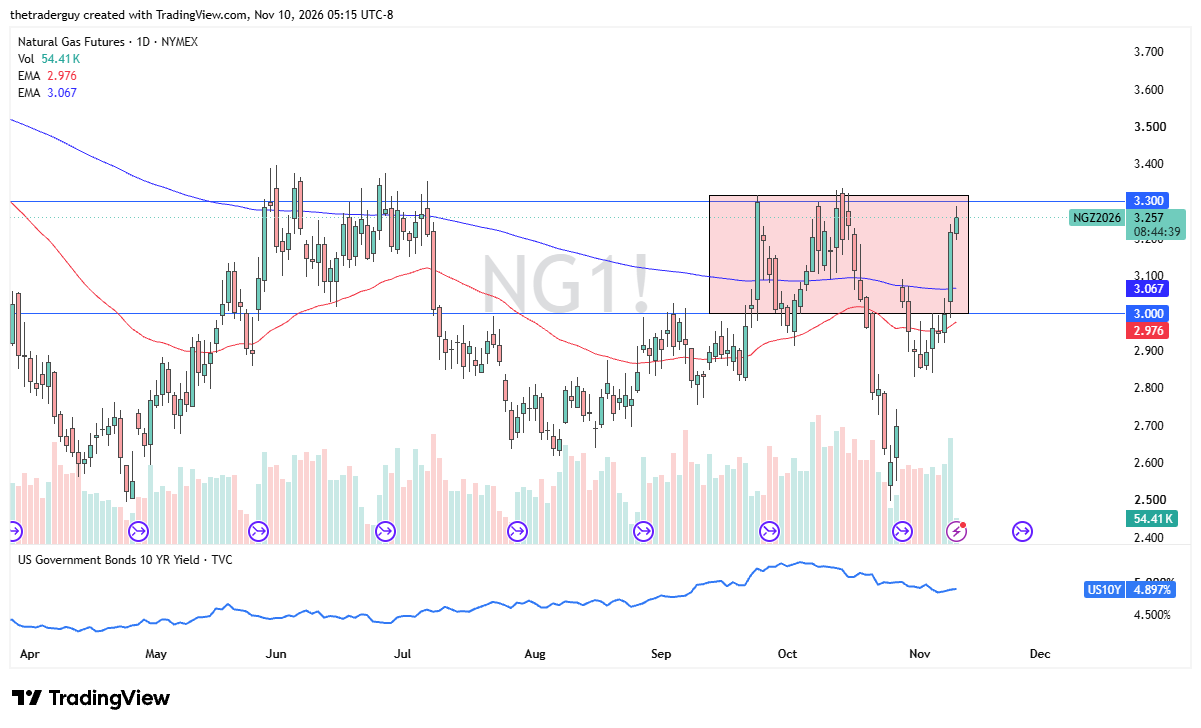
From a technical analysis standpoint, it does look like natural gas has tested the $3.30 level, and it looks as if it is going to continue to offer a bit of resistance. Ultimately, natural gas is a market that is very volatile, and pullbacks at this point in time, which I would expect from a technical analysis standpoint, should continue to be buying opportunities, especially if we continue to see the 200-day EMA defended.