


European shares are slightly lower and U.S. equity futures higher during Monday’s European session as we drift into the cash session in New York. We are starting to see a little bit of momentum follow-through, with the S&P 500 gaining right along with the DAX in Germany, as people are celebrating the idea that the Iranians are open to negotiations.
Elections in America Tomorrow
That being said, the markets might be a little bit cautious ahead of Tuesday’s U.S. midterm elections. The U.S. manufacturing survey showed expansion strengthening rather than fading. All of that is starting to translate into higher equities. The ISM’s October manufacturing PMI rose to 55.5 from September’s 54.5. Production climbed to 59.0 from 56.7, while new orders edged up to 55.5. Employment remained in expansion at 52.4, although it did slow down slightly.
NFP on Friday
The real test, of course, will be Friday when the employment numbers come. Inflation detail offered a little bit of encouragement. ISM’s prices index fell to 75.2 from 77.9, indicating that price increases remained widespread, even as the reading did moderate a bit. Supplier deliveries slowed further. The interpretation that I have from this is that stronger activity alongside continued cost pressure limits the case for treating a decline in oil as enough evidence that inflation is completely under control.
This matters after last week’s policy decision, as on October 28, the Federal Reserve maintained its target range of 3.75% to 4% by a 10-to-2 vote. Lisa Cook and Beth Hammack both preferred a quarter-point increase. The statement described economic activity as expanding strongly and inflation as elevated.
For international investors, the implication is somewhat conditional, in the sense that if incoming data reinforce the case for tightening U.S. policy, shorter-term Treasury yields and the dollar could receive some support. Higher discount rates could simultaneously weigh on equity valuations. However, a stronger growth situation can also support corporate earnings, so a firm activity report does not automatically mean falling stocks.
Gold Price Forecast
Every new Gold analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Gold forecastsECB and European Pressures
Europe faces a different set of pressures. On October 29, the European Central Bank left its deposit rate at 2.5%, its main refinancing rate at 2.65%, and its marginal lending rate at 2.9%. It did warn that the larger, longer-lasting energy shock could lift inflation while reducing growth. The ECB also said financing conditions had tightened.
Those official assessments explain why a drop in energy prices can matter well beyond the commodity market. Sustained relief in fuel costs could improve household purchasing power and company margins while reducing some of the inflationary pressure. That being said, a brief market decline doesn’t necessarily immediately reverse the accumulated cost or tighter credit conditions. The ECB explicitly retained a meeting-by-meeting approach and could not be bothered to commit to a future rate path.
Oil Dropped Early
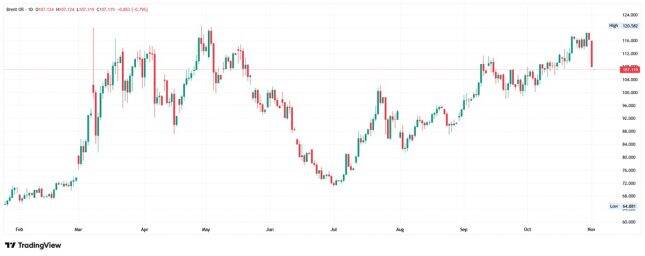
Brent futures were down at one point by as much as 6% early in the day, as there are hopes surrounding Iranian negotiations. That being said, it remains to be seen whether or not that carries through, as this is a game we’ve been playing for months. Lower energy costs could improve the outlook for importing economies, potentially helping their currencies, but exchange rates will also reflect relative yields and international investment flows. A stronger European growth outlook could support the euro, while comparatively restrictive U.S. monetary policy could work in the opposite direction.
JOLTS, ISM Services, and NFP
The next major test will be Tuesday’s JOLTS report at 10 a.m. Eastern, Wednesday’s ISM services report at 10 a.m. Eastern, and, of course, Friday’s employment report at 8:30 a.m. Eastern. These releases will give us a heads-up on whether or not there is resilient demand amid mounting financial stress, or if things start to unravel.